
Levers to improve financial performance
Cost control (also known as cost attainment or cost management) focuses on identifying and reducing business expenses to increase profits. Cost controls are the levers businesses pull to improve financial performance. Businesses use cost controls to monitor, evaluate, and enhance the efficiency of departments, business segments, divisions and product lines. All efforts to control costs must be carefully planned to achieve the intended results.
For successful cost control measures to emerge, management needs to focus on two key activities:
- management and supervision of behaviour
- evaluation of performance.
In planning cost control measures, management utilises two types of control mechanisms.
- Feedforward: provides a basis of control at the point of action (decision point).
- Feedback: providing a basis for measuring the effectiveness of control after implementation.
These are all part of the ongoing process of improving a business’s financial performance. Now that your goal is set, where do you actually start? The best place is, not surprisingly, with the budgets themselves. By understanding the budgets it will enable you to (1) organise and coordinate the selling, distribution, service and administrative functions, and (2) take advantage of business opportunities.
By considering the budgets first, you will be able to segment a business into different components (or ‘cost centres’). This is important because those segments are where the respective leaders take cost control actions. Viewing a business through the lens of its budgets also reveals the expected level of activity and responsibility of each person, as well as the resources that should be used within each ‘cost centre’.
Before we take any more steps, let’s stop and consider how cost management has evolved over the past four decades. This will help us to contextualise the approaches to cost control we see today.
The evolution of cost management
Below is a graphic from Deloitte showing how cost management has evolved since the 1980s. Note the defining features of each period, pay attention to the shift of focus over time, and then see the summary that follows.
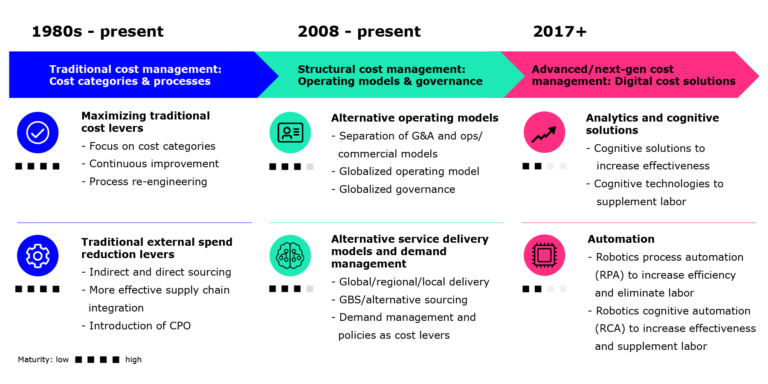
Source: Deloitte [1]
What should be clear is that the evolution of cost management has matured from focusing on cost categories and processes to digital cost solutions. Advanced analytics and technological progress in automation mark a dramatic shift from mere maximisation and external reductions from decades past.
“Now, we are seeing the rise of advanced, next-generation cost management solutions that harness the power of digital technologies to boost efficiency and effectiveness, and to enable fundamentally new business models and new ways of working that dramatically reduce costs.” – Deloitte, Thriving in uncertainty in the age of digital disruption (2017) [1]
-
Developing cost management capabilities. The key focus areas include forecasting, budgeting and reporting, new policies and procedures and IT infrastructure, IT systems and business intelligence platforms.
-
Implementation remains the biggest challenge. Implementation of cost control strategy remains as a critical barrier to cost management.
-
Tactical actions remain predominant. Many companies continue to focus on tactical cost actions such as streamlining business processes and reducing external spend vs strategic cost initiatives such as outsourcing, centralising, and business configuration. Tactical focus limits the cost savings.
-
Cost-cutting: In broader terms, cost-cutting is a result of corporate restructuring, divestment of peripheral activities, layoffs and outsourcing.
-
Outsourcing: Outsourcing of technical and professional jobs is becoming more and more common. It’s the payment by a company for a business function that was formerly done in-house. Outsourcing can be done if the firm is incurring higher overhead costs as compared to the outsources or vice versa.
-
Digital disruption: Digital disruption and the technologies that drive it are expected to be defining factors that sustain cost reductions and margin improvements.
Have you witnessed or been a part of a scenario where the financial performance of a business was drastically improved? What were the most important contributing factors? If not, what do you think the most important contributing factors would be?
Share your thoughts in the comments.
References
- Thriving in uncertainty in the age of digital disruption [Document]. Deloitte; Dec 2017. Available from: https://www2.deloitte.com/content/dam/Deloitte/se/Documents/process-and-operations/GlobalCostSurvey2017.pdf
Financial Analysis for Business Performance: Data-Driven Decision Making

Financial Analysis for Business Performance: Data-Driven Decision Making





